The envelope looked the same as last year’s. Same window, same carrier logo in the corner, same stiff fold. What changed was the figure on the second page — the one that used to sit close enough to the prior term that you paid it and went back to the dishes.
Across the street, a neighbor with a similar sedan and a similar commute opened a letter that barely moved. Same month. Same metro. Two kitchens, two numbers. People treat that as a slight. Underwriters treat it as geography, credit, miles, a ticket from April, a teen added in August, and whether the car sleeps in a garage or on the street.
ZIP codes are blunt instruments, but they are not imaginary. A town line can change loss history. A short hop in annual mileage can change the tier. A lapse from three years ago can still sit in a file. None of that is cinematic. All of it shows up when a policy renews.
This page is advertorial content from Auto Policy Guide. It features Auto Insurance Quote Compare Journal, a comparison experience from Quote Compare Help. We may be compensated if you continue through a link to review options. The opinions expressed are those of the author. This site is not affiliated with any specific insurance carrier unless explicitly stated.
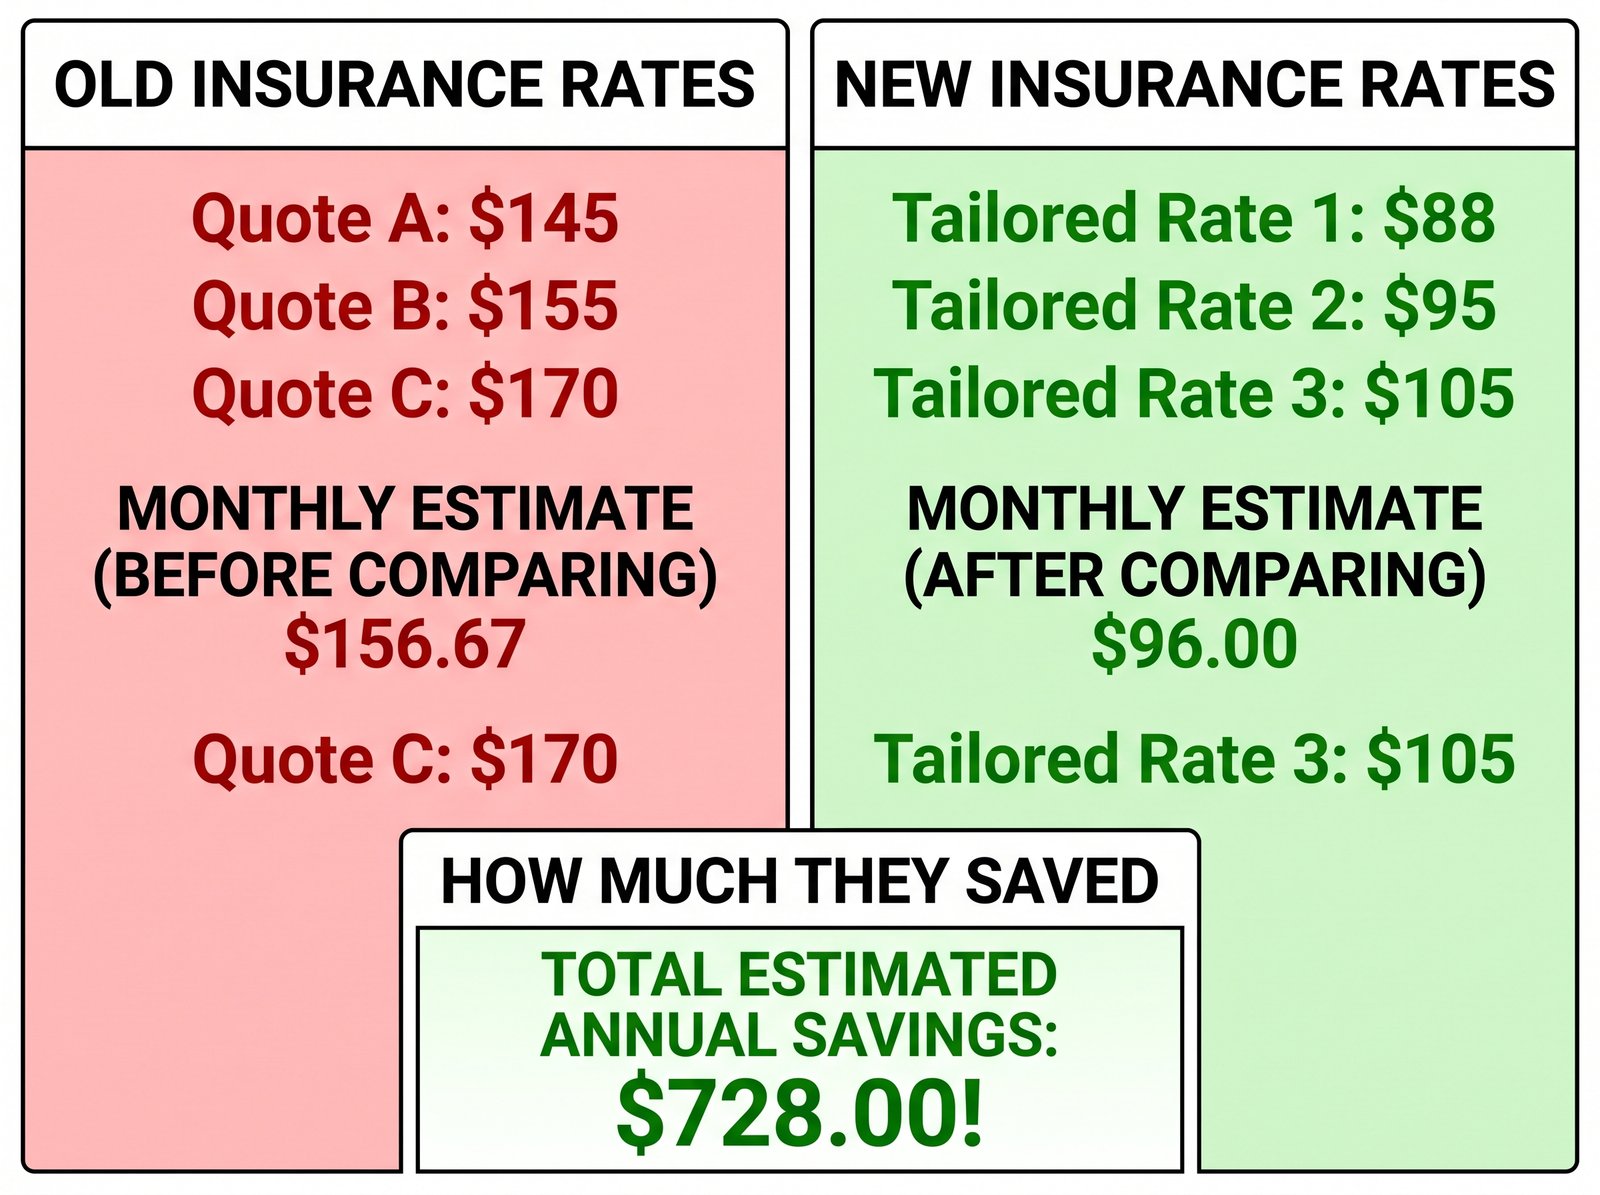
Shopping more than one company before you sign a renewal is ordinary consumer hygiene — the same instinct that makes someone look at two hardware quotes before replacing a water heater. Comparing quotes may help some drivers see options available in their area. Some drivers may find a lower-priced alternative. Many will not. Actual insurance rates are not guaranteed and will vary.